Equipment sales, hire & support
helpdesk@ivsmh.com01226 805282
AntOn by Jungheinrich offers · PTL from £775 + VAT · CBH from £14,995 + VAT · Ends 5 November 2026See prices →
MiMA · Supplied by IVS

MiMA multidirectional forklifts

Specialist handling options for timber, steel and other long or awkward loads

Request a tailored quoteSpecification and current availability confirmed by IVS

Available to order — delivery in approximately two weeksYour written quotation confirms the delivery date and selected configuration.

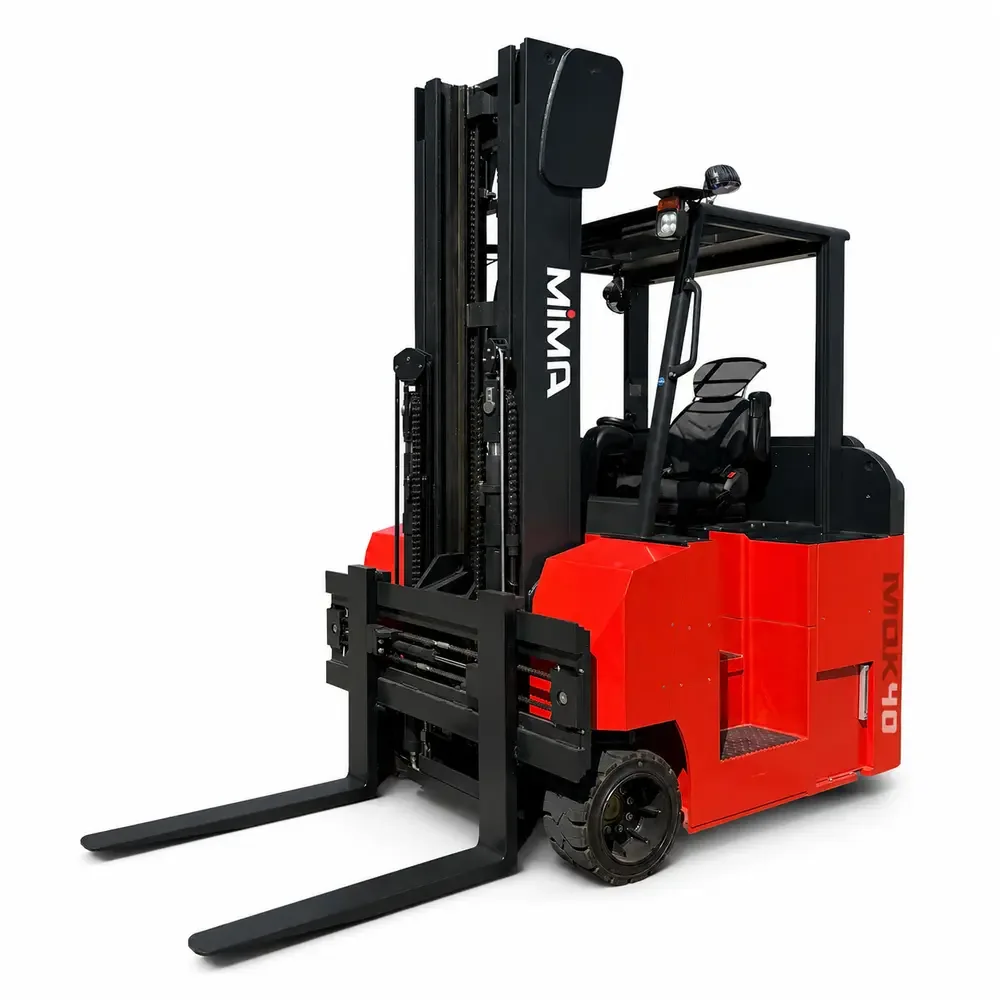
MiMA MQK40 multidirectional forklift for long loads
Manufacturer range image · configuration may vary

At a glance

Range to discuss
MQ multidirectional forklifts
Work
Long-load handling and storage
Selection
Load length, weight, centre and route
Pictured
MQK40 multidirectional forklift

Range information is a starting point for selection. The written IVS quotation confirms the specific machine and equipment supplied.

Where this equipment fits

Multidirectional handling is worth considering when long loads make conventional pallet routes difficult. Review how the material is collected, transported and stored, including turns, loading areas and access into the building.

What to check before choosing

Supply the full load dimensions and weight, load centre, support requirements and lift height. Include the narrowest part of the route and any surface changes. A nominal capacity does not establish suitability for every long load.

Plan the complete package

Discuss attachments, load support, floor conditions and maintenance access before selecting a configuration. IVS can compare the requirement with sideloader and specialist handling options.

What details matter most for a long-load enquiry?

Load length, width, weight, centre of gravity, support points and the complete operating route. Drawings and photographs help IVS understand the handling requirement.

What is included in the price?

Ask for the truck, battery and charger where applicable, delivery, preparation and warranty terms to be set out in your quotation. Mast and attachment choices can affect both capacity and price.

Discuss planned maintenance and repairs and Thorough Examination alongside the purchase. Servicing and examination are separate activities; your quote should make the agreed scope clear.

Manufacturer technical information

View the supplier’s range information

For IVS pricing, availability and support, use the quotation form below.

Buying equipment · Tax allowances

Your forklift purchase may qualify for a 100% tax deduction

Eligible businesses may be able to deduct the full qualifying cost from taxable profits through full expensing or the Annual Investment Allowance. The saving depends on your tax position and purchase arrangements. Ask your accountant to confirm eligibility before ordering.

Which allowance could apply?

Full expensing: companies subject to Corporation Tax can claim a 100% deduction for qualifying new, unused main-rate plant and machinery. Equipment bought to lease out is generally excluded.

Annual Investment Allowance (AIA): eligible businesses can claim a 100% deduction for qualifying purchases, including eligible second-hand equipment, within their available allowance. The usual limit is £1 million for a 12-month accounting period; adjustments and sharing rules can apply.

The equipment brand or power source does not, by itself, establish eligibility. Your accountant should check the asset, business use, accounting period and available relief.

What does a 100% deduction mean?

It reduces taxable profits by the qualifying cost. It is not a refund of the purchase price.

Illustration: a £20,000 qualifying purchase could reduce Corporation Tax by £5,000 where the full deduction reduces profits taxed at 25% and sufficient taxable profits are available. This is an example, not a guaranteed saving. VAT recovery is separate; later disposal can create a tax adjustment.

Buying outright, hire purchase or rental?

Qualifying hire purchase can be eligible for capital allowances. For AIA, HMRC states that when the item starts being used, the capital payments under the contract can qualify; interest is excluded from AIA.

Ordinary rental does not normally give the customer capital allowances on the equipment purchase. Ask your accountant to check the specific agreement, tax treatment and claim timing.

Official HMRC references

Use these government sources to check the rules with your accountant:

Guidance checked 7 October 2026 · General information, not individual tax advice · Tax rules and circumstances can change

Let’s get to work

Get your IVS quotation

Tell us your load weight, lift height, daily hours and target date. We will confirm the specification, availability, price and support for your site.

01226 805282
helpdesk@ivsmh.com

Units 17–23 Sandybridge Lane
Shafton, Barnsley
S72 8PH

For a breakdown or time-sensitive enquiry, call the team to discuss availability.

Tell us what you need. Fields marked * are required.

Loading secure enquiry form…

We use your details to respond to your enquiry. Read our privacy notice.